Fair warning - this is a beast of a post and may bore you to tears if you aren't interested in money. Feel free to just come back tomorrow for a post about cake.
There are a million ways to make a budget and most of them are described in detail somewhere on the internet. I'm not an expert, but I've had a few questions about how I developed my budget and recently I've helped a few family members with budgets and it finally motivated me to put this post together. If you're interesting in budgeting, or if you're just voyeuristic and love hearing about how other people handle their money (no shame here), read on.
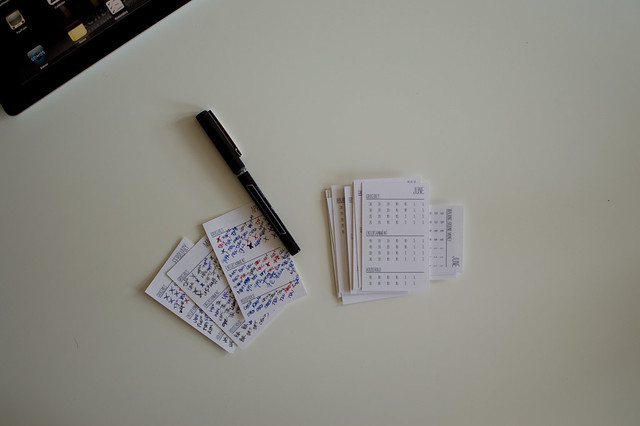
{budget cards}
Here's my disclosure - Money is individual. What works for one person may not work for another. What works for you in this stage of your life may not work for you later. Don't get discouraged. Just keep playing around with it until you find something that is working for you and then stick with it.
My needs are fairly simple.
- I want a breakdown of how much I can spend in various categories each month.
- I want to spend less than I earn and to put some money in savings.
- I don't want to have to track every single expense. I will never be the person entering all her receipts every day. So my budget needs to survive without too much maintenance and it needs to leave me a little wiggle room.
Here is a link to the spreadsheet I use for budgeting (I deleted my own numbers and notes because even though I'm pretty open about finances I apparently draw the line somewhere). You can download it and fill it in or you can create your own from scratch or do this on pen and paper. I prefer the automated spreadsheet because it makes it very easy to play around with reducing/increasing your amounts in various categories while you figure out your goals. You will need to download the spreadsheet from Google Drive to edit it. When you click on the link, take a look in the upper left corner of the screen and you should see a downward facing arrow icon. That will let you download the spreadsheet to your own computer.
Filling in the spreadsheet:
Figure out what you bring in each month, after taxes. Enter that in the income cell. This is what is actually deposited in our bank accounts, which doesn't include, for example - our health insurance premiums, union dues, my bus pass, anything that is taken out pre-tax.
Start filling in your expenses on the lines below. Delete and add lines as necessary. Feel free to move things between one category and another. I roughly follow
the balanced money formula and I categorize our expenses into needs (red), wants (green) and savings (blue). But what you and I consider needs might be different. For example, I put our haircuts in the needs category but technically they are wants because we could just buy a Flowbee and do them at home if we really had to. I count our student loan payments as savings, which I know might seem odd, but my reasoning is that when we're done paying them off (please god, sometime in the next decade) that monthly amount will start flowing into a savings account instead.
My point is that the categories are personal and you shouldn't spend too much time agonizing over them. Recategorize as you like, add lines where you need them. You'll notice I don't have medical expenses included here and that's because I use
an FSA account and have a certain amount of money deducted from my paycheck each month. In my system, if I don't see the money come into my bank account it doesn't exist. I don't want to have to think about any numbers I don't have to think about.
Filling in the categories might be difficult if you aren't completely sure what you spend every month. You have two options.
Option 1: You can go back through your credit card statements and track your spending in each category. For the best picture you should do several months, ideally a whole year to catch any seasonal variations in spending. Obviously this works best if you almost exclusively use credit cards.
Option 2: The second option is to just not worry too much about it and set the numbers as best you can. I recommend doing this if you find you're getting completely hung up on the data.
An imperfect start is always preferable to indefinitely putting something off. When I started our first budget I didn't really know what we were spending so I entered goal numbers in each category. I later realized some of the goals were well below what we had been spending but (surprise!) we were able to meet the goals anyways. Sometimes a lack of information can be useful.
Take a look at where you stand. Do you have money left over each month? I aim for a $50 - $100 surplus.
Do you have savings? You'll notice that I use several savings accounts. I take full advantage of the CapitalOne* (formerly INGdirect, RIP orange lion!) savings accounts and set up new ones for anything I feel like saving for. I have a personal savings account, a joint long term savings account that we never touch (for big ticket items like a house (ha!), a car, etc), a joint short term savings account that we use for car repairs, vacations and pricey lamps, a Circe savings account that we use for any dog expenses, and a holidays savings account that we use for the sudden bump in expenses we see in November/December (that one is new this year and I think it's going to be really nice to have).
If you entered your exact expenses and now want to start adjusting for a new budget, make a copy of the entire sheet (it will show up as a second tab in the workbook) and rename it. Then start messing with the numbers. This is the good part. See what happens if you lower one expense and decide where you'd like the extra money to go. I spend some time each year recalibrating (which is more fun if you're doing it because of a raise vs. an annual rent increase). When we were contemplating our move, I set up multiple tabs with different rental amounts and it gave us a really concrete understanding of how our lifestyle would change based on the new rent at different levels. It convinced us that taking a less expensive apartment would absolutely be worth it.
When figuring out your budget, make sure you keep a small cushion in there. As I mentioned, I like to have $50 - $100 left over each month. This insulates us if we go over on any of our regular categories in any given month.
Once you have a budget you're most of the way there! Don't drop the ball yet, though. Implementing the budget is a separate process.
Try to keep a full month's expenses in your checking account, untouched. Apparently this is a thing and it's called living on your last paycheck. I didn't realize it was a
thing when we started it, I'm just miserly and terrified of ever paying overdraft fees so I keep a cushion in our account at all times. It's extremely helpful when one of you gets paper checks and isn't so great about getting to the bank to deposit them. Ahem.
Automate your savings. Hopefully there was enough left in your budget for savings. Set that up to automatically transfer over every month. I do mine at the beginning of the month but that's mostly a relic of the times when I was paid once monthly.
I also automate easy bills where I know the amount each month. This includes student loan payments, car insurance and all utilities. Sure, our gas and water vary by a few bucks each month but since we live in an apartment the fluctuations are pretty minimal.
I do
not automate our credit card bills. We do all our spending on credit cards (points, protection, easy to track) and then pay them off each month. I know roughly what our bill on each of our two cards should be based on our budget. I worry that if I automated the bills it would be too easy to get lax about checking them regularly and I don't want to get caught off guard by credit card fraud. I do have an automated minimum payment set up to go through the day my bill is due. This way if I forget to pay a bill I don't get hit with fines. Yes, I really do hate fines. To date, I haven't forgotten a payment but I like knowing I have some back up.
Figure out a tracking system that works for you. I use
the budget cards we designed, although I admit I long for an app that would do exactly the same thing.
The critical thing for me is that I don't track all our spending. I don't worry about any of our recurring bills - those are budgeted for and I don't have to track them. The only categories we track are groceries, joint entertainment/eating out and joint household. We each track our personal spending to make sure we're staying within our allowances.
I let everything else go. I don't track haircuts, gas, cell phone bills, laundry, etc. If it's built into the budget as a line item, I have the money for it. This helps a lot if you tend to be lazy. Or cheap. I would avoid going for haircuts because it just seemed so expensive. But I feel better about myself if I get my hair cut. If the haircut is built into my budget, I know I have the money and I will go and not feel guilty. If there is something you know you should do for yourself but you find yourself not doing it, build it into your budget. Therapy? Biweekly massage? Manicure? Put it in your budget (decrease your allowance accordingly) and you'll be more likely to do it. It's a total mental thing because it's all just a big pool of money, but I find the line item really helpful in that respect.
There are tons of great budgeting tools out there and I won't claim to be the authority but this simple system has worked really well for me and been helpful when I've talked people through some budgeting issues. If it helps anyone reading, I'll be thrilled. If you have questions, or if you would just like to make fun of me for being such a nerd, leave it all in the comments and I'll get back to you. I can talk about money ALL DAY LONG, guys.
*If you're interested in opening up a CapitalOne account and don't have one already, I have
a referral link right here that should give you a small bonus when you open an account with a deposit of at least $250. This isn't a special blog-gy thing (do I need to officially state that CapitalOne doesn't even know I exist? They don't), just a standard customer offer. I haven't used this in forever, but it looks like we each get $20. But of course, you don't need a referral. You can just go directly to the website and
sign yourself up. I find having separate savings accounts hugely helpful and as far as I can tell, they have the easiest system and they make it simple to share accounts with your partner.
Related posts:
How we combined our finances after we got married
Setting up a budget strategy that works for us
Reflections on a full year with our new budget strategy